

This article is a part of Mind Your Business, a weekly review of the most significant business news sent to subscribers every Monday morning. If you haven’t signed up yet, you can do so by clicking here.
Currently, the Canadian economy is grappling with two distinctly different challenges.
On one side, inflation rates are elevated and continuing to climb. Up to now, price hikes have been largely confined to energy. Last month, inflation rose to 3.1 percent, but core indicators (which exclude more unstable elements) remained low.
However, as observed in the United States, such containment may not last indefinitely — and once price increases permeate other sectors, it can be challenging to control them.
On the flip side, the economy is sluggish, and we have yet to fully assess the repercussions of the latest round of tariffs.
These two competing crises present a complex puzzle for the Bank of Canada.
Typically, weak growth would lead the central bank to reduce interest rates to stimulate economic activity. Yet, the rising inflation compels the bank to consider increasing rates to cool the economy and prevent rapid price increases.
Two separate issues — each requiring solutions that contradict one another.
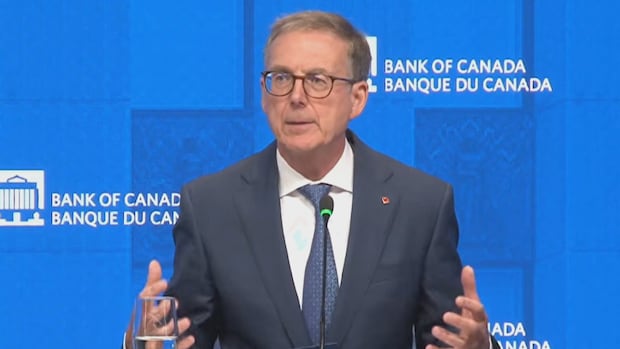
Bank of Canada governor Tiff Macklem expresses hope for a return to a ‘more normal’ Canada-U.S. relationship but does not expect to revert to the previous status quo under an American administration that supports tariffs and protectionism.
One by one, the majority of major economic institutions in the nation have revised their predictions. Most now anticipate that on Wednesday, the Bank of Canada will raise its benchmark overnight lending rate.
They present the economic rationale for their predictions, but as Frances Donald and Nathan Janzen from RBC Economics point out, the bank views this year’s inflation spike through the lens of the previous surge — the pandemic shock from 2022 to 2023.
“The cautionary lessons from the post-pandemic inflation spike … showcased how supply-side shocks and enduring cost pressures can rapidly overwhelm an economy,” Donald and Janzen wrote in a client note last week.
As a result, many economists are now convinced that the bank will proceed with a rate increase, even if not all agree that it is the right course of action.
Donald and Janzen assert that a quarter-point hike would not significantly alter their outlook for the economy. (They had, in fact, based their forecast on the expectation of rate increases next year.)
“Ultimately, the implication of a rate hike on Oct. 28 carries a broader significance that we should not overlook: Central banks are less patient with inflation than they may have been previously, and they are prepared to act preemptively to mitigate it,” they noted.
-
Bond yields are soaring to multi-decade highs. What does that mean for Canadian consumers?
-
Sign up for Peter Armstrong’s weekly newsletter here
If we could magically rearrange the timing, we would prefer the economic data this week to be released in reverse order. The interest rate decision is scheduled for Wednesday, followed by GDP figures on Friday.
GDP growth stagnated in July (zero percent growth), and August is expected to show a modest increase of 0.1 percent. However, new tariffs were implemented during that month, adding uncertainty to the forecast.
Uncertainty has become a constant factor.
Both the Canadian economy and consumers have demonstrated greater resilience than initially anticipated. However, each new challenge chips away at Canada’s growth potential.
On a more positive note, we can also expect an update on the Bank of Canada’s forecasts this week. The Monetary Policy Report provides an in-depth analysis of the central bank’s expectations for the economy.